
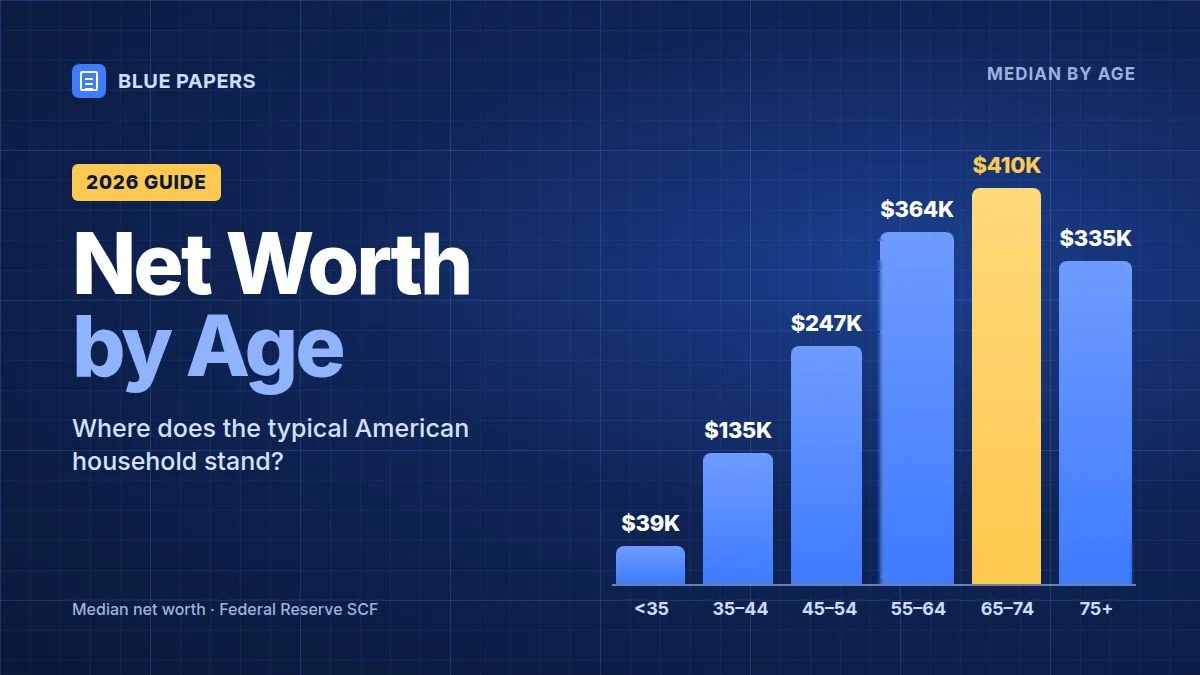
Net worth by age: In the Federal Reserve’s latest survey, the typical (median) American household under 35 had a net worth of $39,040. For ages 35–44 the median was $135,300, and at 45–54 it was $246,700. Net worth peaks at ages 65–74, at a median of $410,000.
Most of the averages you’ll see online are four or five times higher than these numbers. They’re accurate, but a few very wealthy households pull them up, so they tell you little about a typical family. Put your own numbers into the checker below to see where you actually stand.
Add up what you own and what you owe. Rough numbers are fine.
Benchmarks: Federal Reserve, 2022 Survey of Consumer Finances, by age of head of household, in 2022 dollars. The median is the typical household. The average is pulled up by the very wealthy. Nothing you enter leaves your browser.
Table of Contents
Net worth by age: the full table
| Age of household head | Median net worth | Average net worth |
|---|---|---|
| Under 35 | $39,040 | $183,380 |
| 35–44 | $135,300 | $548,070 |
| 45–54 | $246,700 | $971,270 |
| 55–64 | $364,270 | $1,564,070 |
| 65–74 | $410,000 | $1,780,720 |
| 75+ | $334,700 | $1,620,100 |
Source: Federal Reserve, 2022 Survey of Consumer Finances (2022 dollars). This survey runs every three years. Results from the 2025 survey are expected in late 2026, and we’ll update this table when they’re released.
Median vs. average: which one should you compare yourself to?
When comparing net worth by age, start with the median.
The median is the household exactly in the middle: half have more and half have less. The average adds up everyone’s wealth and divides by the number of households, so a few billionaires can pull it far above what most families have.
Here’s how it works. Put nine teachers and one tech founder in a room. The average net worth might be $5 million, but no one in the room is anywhere near that. The median tells you what a teacher actually has.
So if you’re 38 with $140,000, you’re slightly ahead of the typical household your age, even though you’re well below the $548,000 average.
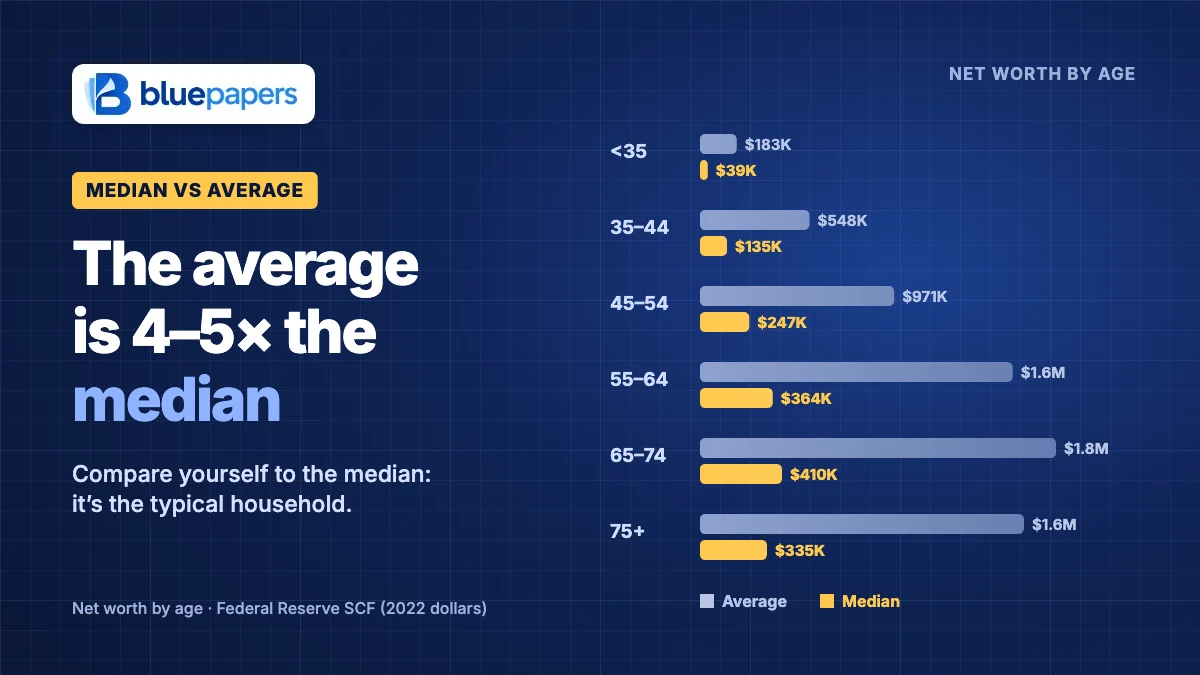
The chart shows the gap clearly. At every age, average net worth by age runs four to five times higher than the median, because a small number of very wealthy households pull the average up. That’s why every net worth by age comparison on this page leads with the median.
What is net worth, exactly?
Net worth is simple:
What you own − What you owe = Net worth
What you own (assets):
- Checking, savings and cash
- Retirement accounts (401(k), IRA, Roth IRA)
- Brokerage investments
- The market value of your home
- Your car and other valuable property
What you owe (liabilities):
- Mortgage balance
- Student loans
- Car loans
- Credit card balances and personal loans
A common mistake: counting your home at what you paid for it, or leaving out the mortgage. Use a realistic current value, subtract everything you owe on it, and stay conservative. Nobody gets rich by overestimating their house.
Two quick rules to check if you’re on track
Net worth by age benchmarks compare you to other households. The rules below compare savings with your own income, offering a different perspective.
1. The Millionaire Next Door formula
From the book by Thomas Stanley and William Danko:
Age × Annual pre-tax income ÷ 10 = Expected net worth
A 40-year-old earning $100,000 “should” have about $400,000. It’s a demanding benchmark, and most people fall short of it. Think of it as a stretch goal.
2. Fidelity’s retirement savings milestones
Fidelity suggests saving this much for retirement, as a multiple of your salary:
| By age | Retirement savings target |
|---|---|
| 30 | 1× your salary |
| 40 | 3× your salary |
| 50 | 6× your salary |
| 60 | 8× your salary |
| 67 | 10× your salary |
This counts retirement savings only, not home equity. It’s a more practical benchmark for most people.
Why net worth jumps in your 30s and 40s
Look at the median column again. Between the under-35 group and the 35–44 group, net worth goes up about 3.5 times, and it nearly doubles again by 45–54.
Three things drive that jump:
- Home equity: For most middle-class families the home is their biggest asset. Every mortgage payment and every year of price growth adds to net worth.
- Compound growth: Money invested in your 20s has had 15–20 years to grow by your 40s.
- Debt payoff: Student loans and car loans shrink or disappear.
That’s good news if you’re behind at 28: the steepest part of the climb is still ahead of you. It’s also why so many Gen Y households, now in their 30s and 40s, are seeing their net worth climb quickly.
Prefer to watch? This video from The Money Guy Show walks through net worth by age benchmarks and what to do at each stage.
Your decade-by-decade blueprint
Use these net worth by age milestones as a guide, not a scorecard. Your income, family size and where you live all shift the numbers.
In your 20s: get to zero, then build the habit
- First goal: a net worth of $0. Pay off credit cards first. They’re the most expensive debt you have.
- Save a $1,000 starter emergency fund, then build it to 3 months of expenses.
- Contribute at least enough to your 401(k) to get the full employer match. That’s an instant return on your money.
- Set up automatic transfers so you never have to decide to save.
In your 30s: get to 3× your salary for retirement by 40
- Raise your retirement contributions to 15% of income.
- Decide whether to buy a home, and run the numbers first with our How Much House Can I Afford? calculator.
- Pay off student loans with an interest rate above 6–7%. Below that, investing usually wins.
- When you get a raise, put at least half of it toward savings.
In your 40s: protect what you’ve built
- Check whether you’re on pace for 6× your salary by 50.
- Make sure you have enough life and disability insurance. Your income is your biggest asset.
- Fund your own retirement before your children’s college costs. They can borrow for school. You can’t borrow for retirement.
In your 50s and 60s: catch up and reduce risk
- Use catch-up contributions (extra retirement contributions allowed after age 50).
- Aim to pay off your mortgage before you retire.
- Shift your portfolio gradually toward more stable investments as retirement gets closer.
What if you’re behind?
Most people are. Net worth by age benchmarks describe millions of households, not a verdict on you. If you’re below the median for your age, don’t panic. Do this instead:
- Track your net worth once a month. What gets measured gets managed.
- Attack high-interest debt first. Paying off a card at 24% interest earns a guaranteed 24%.
- Raise your savings rate by 1% every six months. It’s small enough that you won’t notice.
- Focus on income. Past a certain point, earning more beats cutting coupons.
Net worth by age: frequently asked questions
What is a good net worth at 30?
The median for households under 35 is about $39,000. A net worth equal to your annual salary, with no high-interest debt, is a strong position at 30. Compare your own number with the net worth by age calculator above.
What is the average net worth at 40?
For ages 35–44 the average is $548,070 and the median is $135,300. The median is the better number to compare yourself against.
Does net worth include my home?
Yes, but only your equity: the home’s current value minus what you still owe on the mortgage.
Should I include my car?
You can, but cars lose value every year. Many people leave them out to get a more conservative picture.
What percentage of Americans have a net worth of $1 million?
It depends on the survey, but it’s a minority of households, and most of them are over 55. Getting there takes time far more often than it takes a high salary.
Data last checked September 24, 2026. This article is for educational purposes only and is not financial advice.
Sources: Federal Reserve, Survey of Consumer Finances · NerdWallet, Net Worth by Age (2022 SCF data) · Fidelity, Average and Median Net Worth by Age · The Money Guy Show (video above)
Read next
- Average Savings by Age
- Emergency Fund Calculator
- Is a High-Yield Savings Account Worth It?
- 401(k) Balance by Age
- How Much Should I Save for Retirement?
Leave a Reply